Life Insurance
Coverage for your family, legacy and business.
Personal guidance to protect your family, plan retirement income, and explore the value of life insurance you no longer need.
Saul L. Appel, CLU, ChFC & Shelley Harrison
Coverage for your family, legacy and business.
Plan retirement income with fixed and indexed annuities.
Sell a life insurance policy you no longer need. We seek competitive offers from qualified buyers.
Whether you need new coverage or want to review a policy you already own, we help you understand your options and choose a practical next step.
Tell us what you want to protect and what coverage you have now.
Discuss life insuranceWe help you explore fixed and indexed annuities based on when you need income and how much access you need to your money. Already own an annuity? We can review it with you.
Tell us about your timing, priorities and any annuity you already have.
Discuss my annuity optionsIf your coverage is no longer needed or premiums have become difficult to maintain, a life settlement review can help you find out whether selling the policy deserves consideration. Not every policy qualifies.
Share a few policy details to start a personal review.
Explore my policy’s valueHelp senior clients explore a possible cash offer before surrendering or lapsing their coverage.
If a client no longer needs their life insurance or premiums have become too expensive, a life settlement may offer another option. With your client’s authorization, we help evaluate the policy and seek competitive offers from qualified buyers.
Request a callback, or add optional non-medical policy details with your client’s authorization. Please do not include health information, medical records or identifying client documents in this form.
Request a client policy estimateWe review the case, discuss what records are needed and coordinate the next steps with you. Before proceeding, we clarify your role, client communication and any compensation arrangement.
Not every policy qualifies. An initial estimate is not a guaranteed offer. Review the client’s remaining coverage needs and alternatives before any policy change.
Saul L. Appel, CLU, ChFC, brings more than 50 years of insurance experience. Shelley Harrison brings 40 years of industry experience. Together, we offer personal, independent guidance for your coverage and retirement goals.
Meet Saul & Shelley →Explore the purchase of an existing policy as a long-term asset, separately from selling a policy you already own.
Beyond selling a policy, qualified buyers may explore purchasing an existing life insurance policy as a long-term asset. Our life settlement purchase strategies for retirement and buy-sell planning are limited to accredited investors and subject to suitability and transaction review.
An accredited investor purchases an eligible existing policy, funds the required premiums and becomes entitled to the death benefit under the transaction documents.
The planning concept is to consider an insured whose independently estimated life expectancy is shorter than the investor’s retirement horizon. If proceeds arrive before retirement, they may become capital for a separately designed income plan.
This is a future lump-sum strategy. The policy does not produce regular retirement income while the insured is living. Life expectancy is an estimate, and proceeds may arrive after the intended retirement date.
An accredited investor or qualifying business entity may explore a purchased policy as one component of a capital reserve for a future buy-sell obligation.
The concept compares the insured’s estimated life expectancy with the anticipated buyout horizon. Proceeds, if received in time, could contribute toward the purchase obligation described in the agreement.
Timing must work independently of the policy. A third-party insured’s death does not coincide with a partner’s death, disability or retirement. The agreement needs reliable funding for its actual trigger, even if settlement proceeds have not arrived.
Illustration only: a 6-year estimated life expectancy compared with a 10-year retirement or buyout horizon. The difference creates a planning interval—not a promised payment date.
The insured may live beyond year 10. Additional premiums and a longer holding period must be considered.
Purchase price and transaction costs. Current policy status and carrier information. Independent life expectancy estimates. Premium requirements and reserves. Ownership, beneficiary rights and servicing.
We also consider longer-survival scenarios, liquidity needs and the consequences of receiving proceeds later than planned.
No. Purchasing another person’s existing policy creates an investment with ongoing premium obligations and uncertain payout timing. Selling your own policy and separately considering an annuity are different transactions.
No. The insured may live substantially longer than estimated. Additional premiums, delayed proceeds and liquidity needs must be evaluated.
No. Tax treatment may differ from personally purchased life insurance. Have your tax adviser review the specific transaction.
Resources: SEC accredited investor guidance.
Talk with Saul or Shelley about life settlement purchase strategies and the review involved.
Explore buy-sell insurance, key person protection and the review of business-owned policies.
Review the agreement’s triggers, ownership, premium responsibility and funding needs with your attorney. Match coverage to the agreement.
Consider the financial effect of losing a critical employee or partner, and the coverage the business needs to continue operating.
A retirement, ownership change or repaid loan may change the need for insurance. Confirm remaining obligations before considering a policy sale.
Talk with Saul or Shelley about buy-sell, key person or existing business coverage.
Meet Shelley and Saul, and explore life insurance, annuities and business planning.
An introduction to annuity options. Benefits and bonuses depend on the qualifying contract and its terms.
Open video →Explore your options before canceling or surrendering a life insurance policy.
Open video →Personal guidance for life insurance, annuities and life settlements.
Open video →An educational scenario for owners and business partners.
Open video →Videos from Appel & Harrison. Videos are educational; eligibility, results and contract terms vary.
Tell us what you want to accomplish. We’ll help you understand your options.
Explore life insurance, annuities, life settlements and business planning. Choose a topic below.
A clear conversation starts with the policy you have and the protection you need.
Write down who or what the coverage needs to protect and for how long.
Bring the policy, latest statement, beneficiary information and a current in-force illustration when available.
Compare premiums, guaranteed values and non-guaranteed illustrations. Ask what funding is needed to maintain the intended coverage.
Ask about conversion deadlines, riders, withdrawals or loans before making changes.
Review what you would give up, new costs and underwriting requirements before ending existing coverage.
Educational guidance. Review the actual policy or contract and consult appropriate advisers. Further reading →
← Back to ArticlesCompare the contract as a whole, rather than choosing from one headline number.
Identify when you need income and the money that must remain available for other needs.
Ask which value can be withdrawn, which value determines income benefits, and what applies at death.
Understand the rate guarantee or index formula and which terms may change.
Review surrender periods, withdrawal limits, rider charges and any market value adjustment.
Confirm bonus vesting, recapture rules and how withdrawals affect benefits. Ask which benefits are guaranteed.
Before replacing it, compare the benefits, guarantees, charges and new surrender period.
Educational guidance. Review the actual policy or contract and consult appropriate advisers. Further reading →
← Back to ArticlesA settlement offer is one part of a decision about coverage you already own.
Consider whether you or your beneficiaries still need the death benefit.
Confirm ownership and review any trust, court order, business agreement or lender interest with the appropriate adviser.
Bring the latest statement, premiums, cash surrender value, conversion terms and an in-force illustration when available.
Review keeping, adjusting, surrendering or selling the policy, including the compensation and net proceeds of a proposed sale.
Discuss taxes, public benefits and the loss of the sold policy’s death benefit before agreeing to a transaction.
Educational guidance. Review the actual policy or contract and consult appropriate advisers. Further reading →
← Back to ArticlesOver 90 years of combined experience. Independent guidance. A personal conversation.
With over 90 years of combined experience, Saul Appel and Shelley Harrison bring a seasoned perspective to insurance and planning decisions. Our independent approach begins with listening and continues with clear explanations.
CLU · ChFC
Over 50 years of experience in life insurance and financial services. Saul’s work includes life insurance, annuities and life settlements, helping individuals and business owners evaluate protection, income and policy-value decisions.
40 years of insurance experience. Shelley brings extensive industry perspective to conversations about coverage and planning, helping clients understand their options and consider their next step.
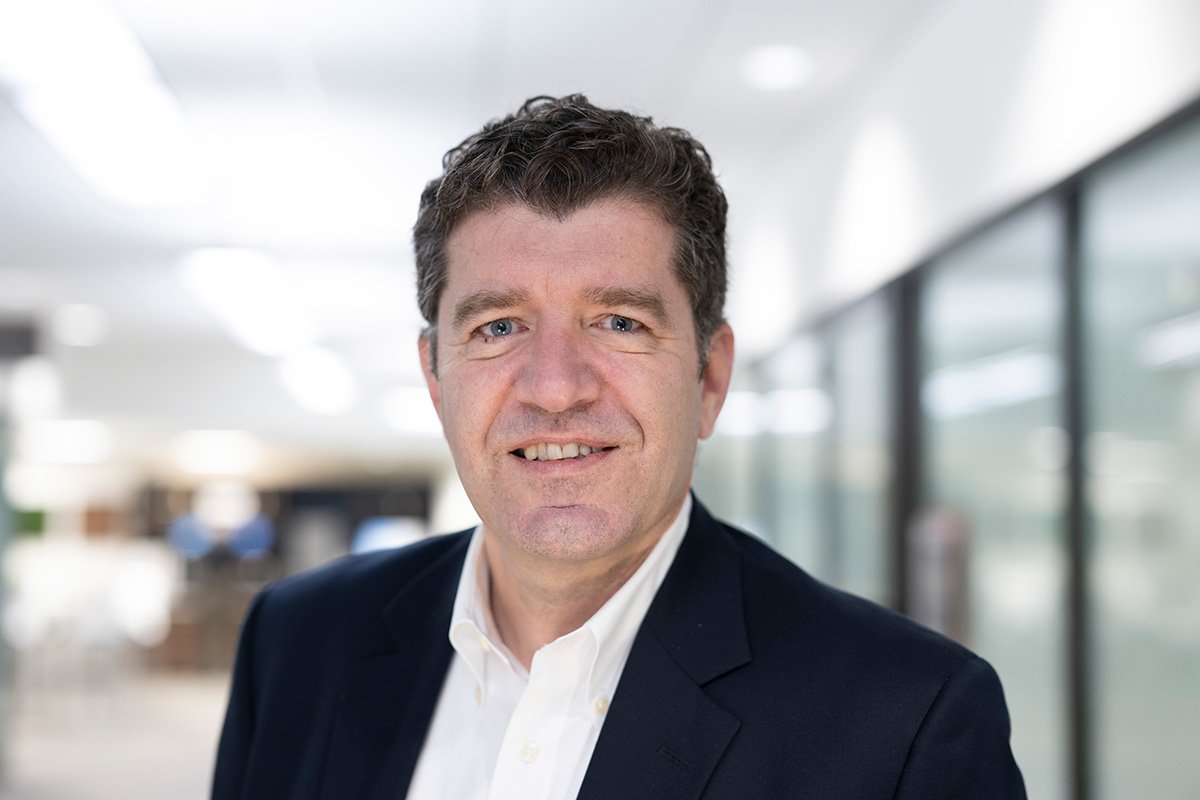
AI & Technology Advisor
Kostas brings more than 20 years of technology and AI experience, including leadership roles at Google, Unifyr and Scorealytics. He developed our integrated AI office to support research, administration and follow-up, helping our team compare options and devote more attention to clients.
He holds a master’s degree in Computer Information Systems from Bentley University and a bachelor’s degree in Finance and Economics from the University of Florida.
Interested in creating your own AI office? Contact Kostas to discuss his technology services.
Licensed in 37 states. Contact us to confirm availability for your state and the service you need.
We start by listening. We review the relevant policy or contract details, explain the choices and tradeoffs, and help you evaluate the next step.
For business, trust or estate matters, we can coordinate the insurance conversation with your legal and tax advisers.
Tell us what you want to accomplish. We’ll help you understand your options.
Share a few details so we can prepare for your call. Don’t have your policy information handy? You can still request a callback.
This callback form is for contact and non-medical policy details only. Please don’t include health information, medications, medical records, Social Security numbers or banking information. We’ll discuss any further information needed on the call.
About: Choose your topic below
Call Saul or Shelley, or email us about your inquiry.
Please do not send medical records, Social Security numbers or banking details by ordinary email. Ask about the appropriate way to share documents.
Start with your monthly income gap, then compare how an annuity could help cover it.
Appel & Harrison · October 10, 2026 · 391 words
A retirement account balance tells you how much you have saved. It does not tell you how comfortably you can live. To answer that question, translate your savings into the income you need each month, while keeping enough money available for expenses that do not arrive on a schedule.
Imagine a couple with regular expenses of $7,000 a month and $4,500 coming from Social Security and a pension. Their starting income gap is $2,500 a month, or $30,000 a year. This is a planning example, not a recommendation. Their travel budget, taxes, home repairs and medical expenses still need a separate place in the discussion.
Write down your own numbers before comparing products. A realistic spending estimate is more useful than a headline interest rate. Include expenses you expect to change when you stop working, such as commuting, and costs that may grow over time.
An annuity is a contract with an insurance company. Depending on the contract and payment option, it can provide income for a stated period or for life. A useful quote should identify when payments start, how much is guaranteed, whether payments continue for a surviving spouse, and what remains for beneficiaries.
A lifetime withdrawal percentage is not necessarily an investment yield. Payments may include a return of your own money. Ask your adviser to explain the difference between interest credited to a contract and the income you can withdraw under a benefit.
Consider three hypothetical buckets: money for regular income, money for near-term needs, and money for longer-term goals. The right balance depends on your circumstances. Committing every dollar to one contract can make an unplanned expense harder to handle.
Before purchasing, ask what happens if you need a large withdrawal. Review surrender charges, withdrawal limits, rider costs and the insurer’s financial strength. Insurance guarantees depend on the issuing insurer’s claims-paying ability.
A useful retirement plan should answer an ordinary question: can you pay your bills and still make choices? Bring your income sources, spending estimate and existing contract statements to a review. Then compare options against the same income goal. The objective is a plan you understand and can comfortably maintain, including during an expensive or disappointing year.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Learn which value receives a bonus and what charges, vesting rules and withdrawal terms accompany it.
Appel & Harrison · October 10, 2026 · 394 words
An annuity bonus can make a proposal look impressive at first glance. But the bonus percentage is the beginning of the comparison. Your decision should depend on what the bonus does for you, what you pay for it, and how the entire contract fits your plans.
Does it increase the account value, an income benefit base, or another value? Those amounts can serve different purposes. An income benefit base may be used to calculate future withdrawals without being an amount you can take as cash. Ask to see each value separately on a sample statement.
Here is a simple hypothetical comparison. A 14% bonus on $100,000 equals $14,000. A 21% bonus equals $21,000. The larger number creates a $7,000 difference at the start, but it does not establish which contract provides the better outcome. Neither percentage should be described as an annual return.
Ask when the bonus becomes fully vested. What happens if you surrender the contract early, make a withdrawal, use an income benefit, or die? Do not assume the same rule applies to every event. Have the relevant contract provisions identified in writing.
If one option has an annual charge, identify the value on which that charge is calculated. For illustration only, 0.95% of a $100,000 charge base is $950 for one year. The actual dollar charge can change as its calculation base changes. This example does not forecast either contract’s future values.
Use matching assumptions when reviewing two proposals: the same deposit, income starting age, withdrawal needs and time horizon. Examine guaranteed values separately from illustrated values. Ask about interest-crediting terms, surrender periods, available withdrawals and death benefits.
For example, a client who may need money for a home purchase in two years should discuss access before focusing on a bonus. Another client planning future lifetime income may have a different priority. Their needs, rather than the largest advertised percentage, should shape the comparison.
Before signing, try describing the bonus in one sentence: which value increases, what it costs, and when you can benefit from it. If the answer is unclear, request a simpler explanation and a written comparison. A well-understood contract is easier to evaluate than a large number without context.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Compare predictable interest with index-based crediting, while reviewing access, charges and guarantees.
Appel & Harrison · October 10, 2026 · 380 words
Two people can have the same retirement savings and need different annuities. One wants to know the interest rate in advance. Another is willing to accept uncertain credited interest in exchange for a formula linked to an index. The useful question is which approach fits your goals and time horizon.
A traditional fixed annuity credits interest under the contract’s stated terms. A multi-year guaranteed annuity commonly sets a rate for a specified period. Confirm the guarantee period, what happens afterward, and whether taking money out early creates charges or other adjustments.
This approach may appeal to someone who wants a straightforward interest schedule. Predictability does not mean unrestricted access. A contract can have a guaranteed rate and still limit withdrawals during its surrender period.
A fixed indexed annuity calculates interest using a formula linked to an external index. You do not directly own the stocks in that index. Caps, participation rates, spreads, crediting periods and other terms can affect the amount credited. Some terms may change at renewal, subject to the contract.
Ask the adviser to demonstrate a positive index period, a flat period and a negative period. A contract may credit zero interest in a period even when you hoped for growth. Protection from negative index crediting does not erase rider charges, surrender charges, withdrawals or other contractual adjustments.
Fixed indexed annuities also differ from registered index-linked annuities, which can expose contract value to market losses. Make sure the proposal identifies the actual product type.
Imagine one person setting aside funds for predictable accumulation and another seeking an optional future income benefit. Their comparisons should use the same deposit and relevant dates, but the questions they prioritize may differ. Neither should choose from a best-case illustration alone.
Request a plain-language summary of guarantees, costs, access and benefits at death. If replacing an existing annuity, review what you would give up and whether a new surrender period begins.
Bring your income needs, emergency savings and current statements to the discussion. An attractive feature is valuable only when it serves a need you actually have. All insurance guarantees remain dependent on the issuing insurer’s claims-paying ability.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Review the purpose, ownership, beneficiaries and funding of the coverage you already have.
Appel & Harrison · October 10, 2026 · 391 words
A life insurance policy may stay in a drawer for years while the life around it changes. Children become independent. A mortgage shrinks. A business grows or changes owners. The policy deserves a review that starts with today’s responsibilities.
Ask what the death benefit is supposed to accomplish now. Would it replace income for a spouse, support someone with special needs, pay a debt, or provide funds for a business transition? Write down the people and obligations it protects.
A policy bought when children were young may still be useful after they leave home, but for a different reason. Conversely, a growing business may create obligations that the original coverage never anticipated. A review should test the purpose rather than automatically propose more insurance.
The insured, policy owner and beneficiary are not always the same person. Find the actual ownership and beneficiary records. Do not rely only on what you remember requesting years ago. If a trust or business owns the policy, involve the person authorized to act for that entity.
Consider a hypothetical remarriage. The owner believes the current spouse is the beneficiary, but the carrier’s record names someone else. Discovering that discrepancy during a routine review is far easier than leaving family members to confront it after a death.
Gather the latest statement and, when appropriate, a current in-force illustration. Ask what premium is required to maintain coverage and which projections are guaranteed. A payment that worked years ago may deserve another look if the policy has flexible funding or changing charges.
For term insurance, identify the level-premium ending date and any conversion deadline. For permanent coverage, review loans, interest and the effect on the death benefit. Confirm that the policy remains in force.
Sometimes the appropriate result is to keep the policy exactly as it is. Other possibilities may include changing beneficiaries, adjusting coverage or reviewing a different funding schedule. Replacing coverage can introduce new costs and underwriting, so examine the consequences first.
Bring your policy, current statements and a short list of what has changed in your life. Ask for a written explanation of the available options. The best review leaves you knowing why you own the coverage, what it costs, and what it is intended to do.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Understand qualifying events, benefit reductions and the questions to ask about a rider.
Appel & Harrison · October 10, 2026 · 385 words
Most people think of life insurance as money for beneficiaries after a death. Some policies also include benefits that may become available during the insured’s lifetime. These features can be useful, but their value depends on the exact policy language and the circumstances of a claim.
A living-benefit provision may address terminal illness, chronic illness or specified critical illnesses. These categories are different, and coverage varies. A diagnosis alone does not establish eligibility under every rider.
Ask which events qualify, how the policy defines them, and what evidence is required. For example, a provision referring to chronic illness may use functional or cognitive criteria rather than simply listing a disease. A critical-illness rider may specify diagnoses and additional conditions.
An accelerated death benefit generally provides access to part of the death benefit before death. Using it can reduce what beneficiaries later receive. The amount paid can also be affected by discounts, charges, benefit limits or other contract terms.
Consider a hypothetical family comparing two policies. They should ask for an illustration of a qualifying claim under each policy, including the amount available and the remaining death benefit. That is more informative than assuming every policy advertising living benefits would pay the same amount.
A living-benefit rider is not automatically equivalent to comprehensive health insurance, disability income insurance or a dedicated long-term-care policy. It may address a narrower need or operate under different triggers. Review existing protection before deciding which gaps still remain.
Ask whether the rider is included, requires a charge, or is optional. Also ask about waiting periods, state availability and whether choosing a benefit changes future premiums or other policy features. Potential tax and public-benefit consequences should be discussed with an appropriate adviser.
If you already own coverage, obtain the rider pages and have the insurer’s requirements explained. Do not assume benefits can be added after a serious diagnosis. If considering replacement, compare underwriting, premiums and the benefits you would give up.
Useful protection should be understandable before you need it. Bring a short checklist to your review: what qualifies, what pays, what remains for beneficiaries, and what it costs. Ask for answers tied to the actual policy, rather than a general description of living benefits.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Review renewal, replacement and conversion before the relevant deadlines pass.
Appel & Harrison · October 10, 2026 · 383 words
The end of a level-premium term period is a decision point, not something to discover when a much larger bill arrives. A policy that has protected your family for years may offer several next steps. Their usefulness depends on your current need, health, budget and contractual deadlines.
Find the end of the level-premium period, the renewal terms and the conversion deadline. They may be different dates. Ask the carrier to confirm them in writing, along with the products available under any conversion privilege.
A hypothetical policy owner might have two years left in a level term but a conversion option ending sooner. Waiting until the term anniversary could eliminate a choice that was previously available. A short review now can prevent that avoidable surprise.
Is the original obligation nearly finished? Or does a spouse, dependent, debt or business agreement still require coverage? Revisit the amount and duration before comparing premiums. Needing less insurance is different from needing no insurance.
List the obligations that must be covered and the resources available to meet them. That gives the discussion a practical starting point rather than making the old policy amount the automatic answer.
Renewal may preserve coverage under the policy’s terms, often at a higher premium. New term insurance may be worth considering if you qualify, but a quote is not a completed underwriting decision.
Conversion may allow eligible term coverage to become permanent insurance without new medical underwriting, subject to the existing contract’s rules. The new premium and available products can differ substantially from the current policy. Ask what is guaranteed and how long the new coverage is designed to last.
For some owners, reducing or ending coverage may be appropriate after a needs review. Do not cancel existing protection while a needed replacement is still being evaluated.
Request a comparison showing cost, duration, guarantees and deadlines. If health has changed, bring that fact into the discussion early. Avoid assuming that last year’s conversion products or underwriting expectations still apply.
The objective is to make a deliberate decision before a deadline makes it for you. Your current policy, a recent statement and a list of remaining obligations are enough to start a useful conversation.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Compare keeping, changing, surrendering and selling coverage before ending a policy.
Appel & Harrison · October 10, 2026 · 392 words
An expensive premium notice can make canceling an old life insurance policy seem like the obvious next step. Before you act, find out whether the policy still serves a need and whether there are alternatives worth evaluating. Ending coverage can close a door that cannot easily be reopened.
Keeping the policy preserves its protection if it remains properly funded. Changing coverage or funding may be possible under its terms. Surrendering a cash-value policy generally means taking the available surrender value and ending coverage. A life settlement involves selling an eligible existing policy to a third party.
A sale is a different transaction from surrendering the policy to the insurer. It may produce a different amount, but not every policy attracts an offer. The death benefit, premiums, insured’s age and health, and policy terms all matter.
Imagine a hypothetical owner reviewing a $30,000 surrender value and a $75,000 settlement offer. The useful comparison is the net amount after disclosed compensation, other transaction costs and potential taxes. Those figures are examples, not an estimate for any particular policy.
Ask for a written comparison and an explanation of what happens to ownership and the death benefit. After a sale, your former beneficiaries generally no longer receive that policy’s proceeds. Include anyone whose financial security depends on the coverage in your decision.
Medical information may be required during an evaluation. Use authorized, secure channels and understand who will receive it. Review the implications for taxes, public benefits and future insurance needs with the appropriate advisers.
Continue maintaining the policy during the review unless you receive a properly considered instruction from the relevant professionals. An evaluation is not a completed sale, and an early conversation does not guarantee an offer or closing.
Gather the policy, latest statement, premium schedule and current in-force information. Explain why you are considering a change. An owner who no longer needs protection has a different situation from one struggling to afford protection the family still needs.
If you are exploring the investment side rather than selling your own policy, our life settlement purchase opportunities are available only to accredited investors. Selling an existing policy does not require the seller to be an accredited investor. Ask which side of the transaction the discussion concerns.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Learn why premiums, policy terms and medical evaluation matter alongside the death benefit.
Appel & Harrison · October 10, 2026 · 393 words
A large death benefit does not automatically mean a large life settlement offer. Buyers evaluate the complete policy and the costs of maintaining it. Understanding those pieces helps a policy owner ask better questions and recognize why two similar-looking policies may receive different responses.
Our life settlement purchase opportunities are available only to accredited investors. This article also helps policy owners understand how an offer may be evaluated; owners do not need accredited-investor status to sell their own policy.
Review the insurer, policy type, death benefit, ownership, loans and guarantees. Identify how long coverage can be maintained and the funding needed to do so. A current in-force illustration is more useful than an old sales illustration when assessing an existing policy.
Consider two hypothetical policies with the same $1 million death benefit. One requires much higher future premiums. All else equal, the larger carrying cost leaves less room for a buyer to pay the owner. Actual offers require a detailed review and may differ for other reasons.
Age and health can influence an independent life-expectancy assessment. That assessment is an estimate, not a date of death. Medical information must be obtained with appropriate authorization and reviewed in context.
The quality and recency of the records matter. A diagnosis from years ago may tell a different story when considered alongside current treatment, testing and functional status. Ask whether the evaluation reflects the latest relevant information.
An investor models possible timelines, ongoing premiums and transaction costs. If the insured lives longer than projected, carrying costs can increase and annualized returns can decline. A responsible evaluation considers those possibilities before establishing a price.
Buyers also have different requirements and investment objectives. One buyer’s decision is not a universal appraisal. Ask your broker how offers are being obtained, what compensation applies, and what documentation is still needed.
For an owner, the relevant question is whether the best available net offer makes sense compared with keeping, adjusting or surrendering the policy. For an investor, it is whether the purchase fits available capital, risk tolerance and the ability to keep paying premiums.
A policy evaluation should explain the assumptions and identify missing information. It should never imply that a headline death benefit, a medical estimate or a quoted return guarantees a particular outcome.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Follow the review, offer, documentation and closing steps of a potential life settlement.
Appel & Harrison · October 10, 2026 · 403 words
Selling a life insurance policy is a process with several checkpoints. A preliminary conversation, an offer and a completed transfer are separate events. Knowing the distinction helps you ask for useful updates and avoid making decisions before the transaction is ready.
An initial review usually begins with the policy type, carrier, death benefit, insured’s age and reason for considering a sale. The owner’s authority to sell must also be established. A trust-owned or business-owned policy may require additional documents and authorized signatures.
Gather the policy and a recent statement. If documents are missing, ask what the carrier can provide. Avoid sending medical records or sensitive personal details through ordinary email when a secure alternative is available.
With appropriate authorization, the review can include medical records and current policy information. The purpose is to understand the policy being offered and the costs of keeping it in force. Requests for clarification or additional records can take time.
For illustration, a review based on a year-old premium projection may need to be updated before an offer becomes final. A status report should identify the outstanding item and who is responsible for it, rather than simply saying the case is moving forward.
Ask how offers were obtained and what each would leave you after disclosed compensation and expenses. Discuss the sale’s effect on beneficiaries, taxes and public benefits. Consider keeping, adjusting or surrendering the policy alongside a sale.
An offer may have conditions or an expiration date. Obtain the details in writing. You remain free to evaluate whether proceeding serves your needs, subject to any agreement you have signed.
Closing can involve contracts, required disclosures, escrow arrangements and carrier ownership and beneficiary changes. Requirements and cancellation rights vary by jurisdiction and transaction. Ask for a written explanation of the sequence, including when payment is released and whether any rescission period applies.
Continue confirming the policy’s status until responsibility has properly changed. Do not assume premiums have become someone else’s obligation merely because an offer was accepted.
Useful updates distinguish documents received, review completed, offer accepted, transfer confirmed and payment released. None should be described as complete before it is verified.
Our life settlement purchase opportunities for buyers are limited to accredited investors. That eligibility requirement is distinct from the process for an owner selling an existing policy.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Review the agreement’s triggers, payment schedule and insurance responsibilities before a crisis.
Appel & Harrison · October 10, 2026 · 387 words
A buy-sell agreement may look complete until a partner becomes seriously ill. Then the business discovers questions the agreement never answered: does illness trigger a buyout, when must payments begin, and who continues paying insurance premiums? These are best addressed while everyone can discuss them calmly.
Death, disability, retirement and a voluntary departure are different events. A life insurance policy typically addresses death; it does not automatically provide the money needed for a living partner’s immediate buyout. Any living benefits must be evaluated under their own contract terms.
Consider a hypothetical business whose agreement requires a purchase when a partner can no longer work. If its only funding is a death benefit, there may be a gap between the obligation and the available cash. The agreement and funding should be reviewed together.
Is the buyout a lump sum or installments? Does interest apply? How is the value determined, and can the remaining business support the payments? Ask your attorney and accountant to test the agreement against a realistic interruption in revenue.
For example, a five-year payment obligation may continue while the business also pays replacement staff and services debt. A cash-flow worksheet can expose pressure that is easy to miss when looking only at the total purchase price.
Confirm policy ownership, beneficiaries and any collateral assignment. Determine whether the agreement addresses premiums after a partner leaves. A departing partner’s personal expectations do not substitute for the owner’s contractual rights or the written business agreement.
If an existing policy might be sold, obtain legal review first. A potential life settlement is an option to evaluate, not an assumed source of money. Coverage may still be needed, and a sale changes the beneficiary outcome.
Purchasing life settlements is another concept entirely. Our purchase opportunities are available only to accredited investors. Proceeds from policies covering unrelated insureds have uncertain timing and cannot be treated as guaranteed cash available when a business partner becomes ill.
Bring the agreement, policies, current statements and business financials to a coordinated discussion. Ask for a written answer to each trigger, payment obligation and premium responsibility. A funding plan should support the agreement under difficult circumstances, rather than rely on assumptions that everyone remembers differently.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Include policy ownership, continuing obligations and possible alternatives in your exit planning.
Appel & Harrison · October 10, 2026 · 391 words
A business sale usually starts with revenue, contracts, employees and price. Life insurance can be overlooked until someone receives a premium bill after closing. Reviewing the coverage before the exit gives the parties time to decide what each policy should do next.
List each policy’s owner, insured, beneficiary, death benefit, premiums, loans and assignments. Identify its purpose: a buy-sell arrangement, key person protection, lender requirement or another obligation. Use carrier records rather than an informal spreadsheet alone.
Imagine a retiring owner who assumes a policy will become personal property. The company may actually own it, and the sale agreement may transfer the company with its assets. Resolve that issue explicitly before signing. This example is a planning illustration, not a legal conclusion about a particular transaction.
Will a lender still require coverage? Are purchase payments dependent on the former owner’s survival or subject to other obligations? Does the agreement require someone to maintain insurance during an installment period? The written transaction terms should answer these questions.
Also identify who pays future premiums and who receives benefits. An arrangement that seemed natural while everyone worked together may become contentious after the business changes hands.
Depending on the policy and legal requirements, options may include keeping coverage, changing its role, transferring it, surrendering it or reviewing a potential life settlement. Obtain tax and legal advice before moving ownership or beneficiaries. Transfers can have consequences that are not visible on a premium statement.
For a possible sale, compare net proceeds with surrender value and the value of retaining coverage. The existence of a secondary market does not mean every policy will receive an offer or that selling is the appropriate result.
Selling a policy the business already owns is different from purchasing another person’s policy as an investment. Our life settlement purchase opportunities are available only to accredited investors. Any proposed investment needs separate review of eligibility, premium reserves, transaction structure and uncertain payout timing.
Ask the attorney, accountant and insurance adviser to agree on the intended treatment of each policy. Retain written carrier confirmations after changes occur. A deliberate insurance review can prevent the business exit from leaving behind an expensive policy, an unintended beneficiary or an obligation nobody expected.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Identify the financial disruption a key employee’s death could create and review a practical funding plan.
Appel & Harrison · October 10, 2026 · 401 words
Some businesses depend heavily on one person’s relationships, knowledge or leadership. If that person dies, the company may face a difficult period even when ownership does not change. Key person life insurance is intended to help address the financial consequences of that loss.
Start with the work rather than the job title. Who brings in major clients, manages essential operations or holds expertise that is difficult to replace? Ask what would stop, slow down or become more expensive if that person were suddenly unavailable.
Consider a hypothetical firm whose founder maintains most client relationships. The immediate challenge could include reassuring clients, hiring leadership and accepting lower revenue while the transition takes place. A coverage discussion should begin with those practical needs.
Create a reasonable worksheet: recruitment, replacement compensation, training, debt commitments and potential revenue interruption. Explain each assumption. A round number chosen without a business rationale may provide less useful protection than a smaller amount tied to a concrete transition plan.
Insurance is only part of the preparation. Document client contacts, delegate responsibilities and train another person to handle critical functions. Coverage can supply funds, but it cannot recreate an undocumented process or a missing relationship overnight.
Clarify who owns the policy, pays premiums and receives the death benefit. Business-owned coverage requires legal and tax review. Employer-owned life insurance can involve notice, consent and reporting requirements; obtain advice before issuance rather than assuming the insurer’s paperwork resolves every obligation.
Key person coverage should also be distinguished from a buy-sell arrangement. One supports the business through a loss; the other addresses the purchase of an ownership interest. A business may have both needs, and the funding should match each purpose.
A person’s importance, the company’s valuation and its available reserves can change. Review coverage when a major employee joins or leaves, a large loan is added, or the ownership structure changes. Assign someone responsibility for checking policy status and premiums.
If a departing employee’s policy becomes unnecessary, review the available alternatives before ending it. Purchasing unrelated life settlements would be a separate investment strategy; our purchase opportunities are available only to accredited investors and are not a substitute for properly designed key person coverage.
A useful review ends with clear ownership, an affordable premium and a written explanation of the business need being protected.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Explore a supplemental reserve concept while recognizing the mismatch between uncertain proceeds and fixed obligations.
Appel & Harrison · October 10, 2026 · 399 words
Business owners sometimes ask whether purchasing life settlements could create capital for a future buyout. The concept deserves a careful discussion: the investment may eventually produce proceeds, but the business cannot choose when those proceeds arrive. A funding obligation and an investment estimate are different things.
Our life settlement purchase opportunities are available only to accredited investors. A business owner’s personal eligibility does not automatically establish that the entity making a purchase qualifies. The proposed owner and transaction must be reviewed separately.
In a life settlement, an investor acquires an existing policy from its owner. The purchaser generally assumes future premium obligations and seeks to receive the policy’s death benefit when the insured dies, subject to the policy and transaction terms.
If the insured is an unrelated person, that person’s death does not coincide by design with a partner’s retirement, disability or death. This is the central timing issue in any buy-sell discussion.
Consider a hypothetical company expecting a future ownership transition but having no certain date. Its advisers might evaluate whether settlement proceeds, if and when received, could contribute to a general reserve. That is a planning concept, not a recommendation or assurance of available funding.
Now consider an agreement requiring $1 million on a specific retirement date. An investment tied to an unrelated insured’s life cannot promise cash on that date. The business needs other resources or contractual arrangements to address the obligation.
The purchase price is only one component. Premiums, servicing and other expenses require funding while the policy remains in force. Stress-test longer timelines, higher carrying costs where applicable, and a period of poor business cash flow.
An owner should ask: could the company maintain both the policy and its operating commitments if proceeds arrived much later than expected? If the answer depends on a quick payout, the proposed reserve is not robust enough.
Your attorney and tax adviser should review ownership, entity eligibility, transaction rules, tax treatment and the buy-sell agreement. The investment’s accounting and servicing arrangements also need clear responsibility.
The appropriate discussion compares this concept with reserves, financing and insurance designed around the partners themselves. Purchased life settlements should not be presented as guaranteed buyout funding. Their possible role is supplemental and depends on a business having the capital and flexibility to tolerate uncertain timing.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Test whether your business can carry the investment through an extended holding period.
Appel & Harrison · October 10, 2026 · 409 words
Accredited-investor status establishes an eligibility category. It does not establish that a particular investment is suitable for your business. A business owner evaluating a life settlement should examine how the investment behaves when the expected timeline does not occur.
Our life settlement purchase opportunities are available only to accredited investors. Verify the status of the proposed purchaser and any additional transaction requirements before considering a commitment.
An estimated life expectancy is not a maturity date. Ask for scenarios extending several years beyond the central estimate. Include every projected premium and servicing cost. A later death benefit may still be substantial while producing a much lower annualized return.
Consider a hypothetical company reserving five years of premiums. If the policy needs to be maintained for ten years, where will the additional money come from? The answer should not depend on borrowing at an unknown future rate or on selling the investment quickly.
Keep working capital, payroll, tax obligations and known buyout installments in the analysis. Money committed to a settlement may be difficult to access when needed. A possible secondary sale is not a promise of a buyer, a particular price or a quick closing.
Ask what would happen during a difficult business year. The company might need cash precisely when additional premiums are due. A reserve should be sized for that combination of pressures, not merely for an average year.
Examine policy guarantees, carrier risk, ownership records, transaction expenses and servicing responsibilities. Confirm who monitors premiums and policy status. Errors in administration can threaten an otherwise carefully evaluated investment.
If considering multiple policies, discuss concentration and shared risks. Holding several policies does not remove uncertain timing, inadequate reserves or dependence on a weak servicing process.
Request the complete purchase cost and the compensation paid to parties involved. Ask whether projected returns are before or after premiums, expenses and taxes, and whether the assumptions are independently reviewed. A projection presented without its cash flows is not enough to evaluate.
An investment proposal should explain what can go wrong and what you would do next. Have your attorney, tax adviser and an independent reviewer examine the structure and assumptions. If a required buyout depends on proceeds arriving on time, arrange dependable funding for that obligation separately. A life settlement can be evaluated only with a clear understanding of its uncertain holding period.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Understand medical review, life expectancy, purchase pricing and the cash flows behind potential returns.
Appel & Harrison · October 10, 2026 · 559 words
A life settlement investment begins with an existing life insurance policy. The current owner sells it, and the purchaser generally takes responsibility for future premiums and seeks to receive the death benefit when the insured dies. Unlike a bond with a stated maturity date, the timing of that payment is uncertain.
Our life settlement purchase opportunities are available only to accredited investors. Eligibility must be verified for the actual purchaser, and accreditation does not eliminate the need for suitability, legal and tax review.
With appropriate authorization, relevant medical records are obtained through secure channels. Reviewers examine the insured’s diagnoses, treatment, testing and other relevant health information. The date and completeness of the records should be identified, along with the date the medical summary was prepared.
AI-assisted tools can help organize records, build a medical timeline and identify information needing further review. Any AI summary must be checked against the source documents. It should support qualified medical or actuarial assessment, rather than be presented as a definitive prediction of an individual’s lifespan.
An independent professional life-expectancy assessment may then inform the investment analysis. Some opportunities may involve estimates under ten years, but that is not a universal characteristic of life settlements. Estimates can differ between evaluators, change with new information and be substantially exceeded in practice.
The death benefit is one part of pricing. Projected premiums, policy guarantees, carrier risk, transaction costs and the range of possible payout dates also affect the amount an investor can reasonably consider paying.
Compare two hypothetical policies with the same death benefit and different annual premiums. The policy with larger carrying costs requires more money after purchase. Similarly, a longer holding period means more years of premiums and a later receipt of proceeds. Neither a large death benefit nor a short estimate guarantees an attractive investment.
Annualized return calculations should include the purchase price, each premium, servicing expenses and the timing of the death benefit. Ask to see the actual cash-flow schedule and whether taxes are included. A simple difference between purchase price and death benefit is not an annual return.
For illustration only, suppose a policy costs $100,000, requires $5,000 at the end of each year, and pays $200,000 at the end of year five. Including five premium payments, the annualized internal rate of return is approximately 11.04% before other expenses and taxes. If the same benefit arrives at the end of year ten with ten premium payments, the rate falls to approximately 3.52%. These invented assumptions are not an available policy, forecast or promise.
Before closing, review policy validity, ownership, beneficiary designations, funding needs and transaction documents. Confirm compensation, escrow arrangements where applicable, and the legal and tax analysis. After purchase, assign clear responsibility for premiums, carrier correspondence, policy monitoring and eventual claim handling.
Request a premium reserve plan that extends beyond the central life-expectancy estimate. Understand whether an early sale is possible and what limitations apply; do not assume liquidity. The policy must remain properly maintained while the investment is held.
A responsible evaluation identifies what is known, what is estimated and what remains uncertain. The most useful question is whether you can carry the investment through a longer-than-expected timeline while meeting your other obligations.
Educational information. Hypothetical examples do not represent an available product or an individual recommendation. Review the actual contract and consult appropriate legal and tax advisers.
← All articlesTalk with Saul or Shelley about your situation.
Tell us about your current coverage and what you would like to accomplish.
Leave your contact details, and Saul or Shelley will call you to talk it through.
Discuss life insurance →Tell us when you need income, how much you need, and how important access to your money is.
Leave your contact details, and Saul or Shelley will call you to talk it through.
Discuss my annuity options →Tell us about the policy you may want to sell. We will follow up to discuss the next steps.
Leave your contact details, and Saul or Shelley will call you to talk it through.
Explore my policy’s value →Request a broker callback or share optional non-medical policy details with your client’s authorization. Do not include health information or identifying client documents.
We can discuss your client’s policy and the next steps by phone.
Request a broker callback →Tell us how to reach you and what you’d like to discuss.
Leave your contact details, and Saul or Shelley will call you to talk it through.
Request a callback →